The Office of the Comptroller of the Currency issued its final rule to implement the Genius Act, the agency said Wednesday.
The rule, set to take effect Jan. 18, represents long-awaited guidance to banks and other OCC-regulated entities that hold, issue and move stablecoins.
Lawmakers, too, this year have attempted to codify a framework for digital-asset use. Early versions of that legislation – the Clarity Act – saw intense negotiations over whether crypto firms would be barred from issuing rewards for stablecoin balances that are “economically or functionally equivalent” to interest-bearing bank deposits.
Bank trade groups argued that if stablecoin issuers were to be allowed to use third-party arrangements to work around a ban, money could flow out of the banking system.
The Senate Banking Committee approved the Clarity Act in May, but the legislation ultimately failed as concerns arose over the potential for conflicts of interest. President Donald Trump, for example, reported $1.4 billion in income from his family’s crypto businesses in 2025, and Democrats in particular pushed for stronger language to prevent government officials from profiting off crypto rules as written.
The OCC’s final rule addresses the stablecoin-yield question but gives itself a wide berth.
Technically, the rule bans direct yield payments to customers from stablecoin issuers, but the OCC notes that it will evaluate yield or reward arrangements with third parties on a case-by-case basis.
"Depending on the facts and circumstances, a payment to payment stablecoin holders through an intermediary might be made solely in connection with the holding, use, or retention of a payment stablecoin or might be made, at least in part, for other reasons," the OCC wrote in Wednesday’s rule.
The regulator also touched on transaction-based payments, noting that such transfers "that did not amount to interest or yield or that were not made solely in connection with the holding, use, or retention of a payment stablecoin would not be prohibited."
The rule does not address parameters related to the Bank Secrecy Act, anti-money laundering and Office of Foreign Assets Control sanctions, the OCC said Wednesday. A separate rulemaking in coordination with the Treasury Department will address those, the agency said.
Further, the OCC will later announce when it will begin accepting and processing applications and waiver requests, the agency said.
“Given the nascency of the industry, the OCC will closely monitor its evolution and structure and adjust the supervisory and regulatory framework for payment stablecoin issuers to the extent necessary,” the agency said in a news release Wednesday.
Treasury Secretary Scott Bessent on Wednesday labeled the final rule a “watershed moment in American finance,” invoking Abraham Lincoln.
“Just as President Abraham Lincoln’s National Currency Act of 1863 established a national framework for bank-issued currency, the GENIUS Act establishes a federal framework for payment stablecoins in the digital age,” Bessent said in a statement Wednesday.
Amplifying language from a 2024 Trump campaign speech, Bessent said the rule “further cement[s] the United States as the crypto capital of the world.”
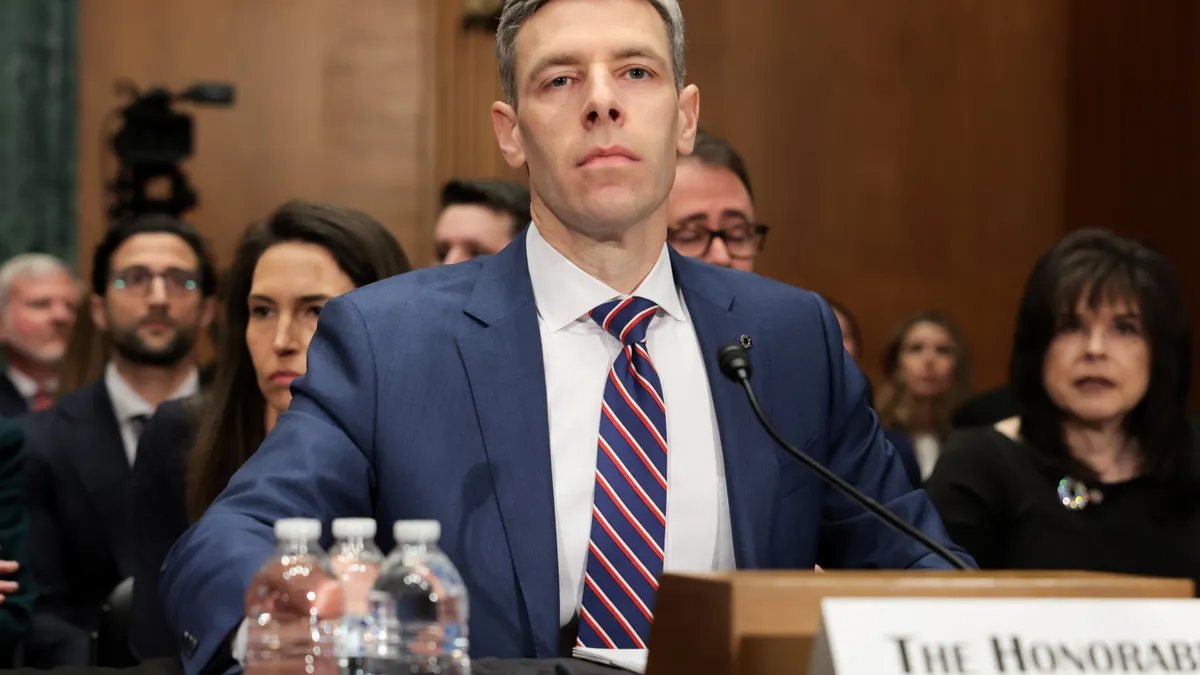
Comptroller of the Currency Jonathan Gould, meanwhile, said his agency is “providing a clear, practical framework for payment stablecoin innovation, with strong standards for reserve backing, redemption, and risk management.”
“The OCC is drawing on its longstanding supervisory expertise to support responsible growth and innovation for this new industry,” Gould said.
In its own statement Wednesday, the Independent Community Bankers of America said it “remain[s] focused on ensuring the [OCC’s] policies protect against the risks that payment stablecoins pose to community bank lending, local communities, and financial stability without appropriate regulatory safeguards and robust implementation of Congress’ intent to prohibit the payment of yield or interest to payment stablecoin holders.”
The trade group cited analysis that found adoption of payment stablecoins could spur a decline of at least $850 billion in community bank lending in the coming years.
“ICBA has called on the OCC to minimize the negative impacts of stablecoins on credit to local communities, establish strong consumer-protection and safety-and-soundness guardrails, and place appropriate operational limits on permitted payment stablecoin issuers,” the trade group said.