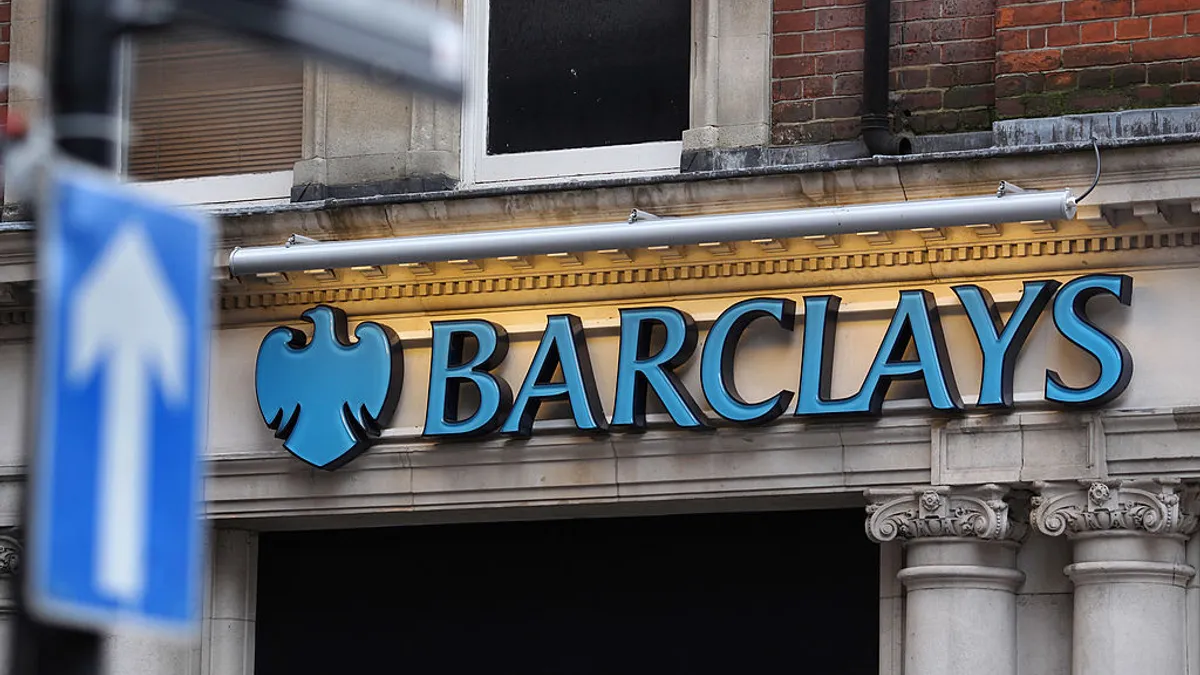
Barclays is cutting roughly 5,000 full-time employees, or 5% of its workforce, this year – with heavy impact expected in “support functions” such as developers – as artificial intelligence boosts productivity, the bank’s CFO, Anna Cross, said Thursday.
The announcement came as the British bank reported its third-quarter earnings, which revealed, among other metrics, a 19% year-over-year drop in revenue from fixed income and currency trading.
The job cuts stole the show, though. Barclays reduced its workforce by about 1,000 employees in the first half of the year, so the remaining 4,000 jobs are expected to be shed by December.
“The changes that we’re making in the third and fourth quarters of this year are sizable,” Cross told analysts on a call Thursday. “They relate both to the simplification of the organization and to some of the impacts that we’re starting to see from AI.”
Barclays CEO C.S. Venkatakrishnan, colloquially known as Venkat, noted the bank intends to “employ AI at scale.”
“But AI is the icing on the cake, not the cake,” Venkat said.
Barclays is far from the only bank this year to hang workforce cuts on the rise of AI.
HSBC in March was reported to have been considering shedding as many as 20,000 mostly middle- and back-office jobs over the next five years in favor of AI.
Standard Chartered in May said it would eliminate more than 7,800 “corporate functions” jobs, such as human resources, risk management and regulatory compliance, by 2030.
But StanChart CEO Bill Winters’ description of the jobs that would be replaced rankled some observers.
“It’s not cost cutting; it’s replacing, in some cases, lower-value human capital with the financial capital and the investment capital we’re putting in,” Winters said during the bank’s May investor day. “We don’t have job losses, but we do have job role reductions in favor of the machines, and that will accelerate as we go forward into AI.”
Winters later apologized amid public criticism that he appeared to be assigning value to the workers inhabiting those roles.
“Where roles do fall away, it reflects changes in the work, not the value of our people,” Winters said in a memo the next day.
Barclays’ Venkat, as it turns out, offered a more tempered assessment of Winters’ comments as the StanChart blowback grew.
“What people do are jobs, and a job is much more than a collection of tasks,” Venkat told Bloomberg in May. “Now you’ve just got to take tasks and make them more productive.”
Roughly 60% of the Barclays jobs on the chopping block are so-called support functions. The bank said it had spent £307 million ($410.5 million) over the first nine months of 2026 on a restructuring that has included staff reductions, investments in technology and a broader overhaul of operations. Barclays expects to incur another £300 million in restructuring costs by the end of December, the bank said.
The total, more than £600 million, is roughly double the bank’s earlier estimate. Barclays, however, is sticking to its cost estimates for 2027 and 2028, Cross said.
On the earnings front, Venkat said he is “disappointed” by the dip in fixed income.
“This is always the house that fixed income built,” he said. “You can be sure this will get my attention.”
Not all of Barclays’ earnings news should come as negative, though. The bank reported third-quarter profit of $3.1 billion, a 12% increase from a year ago.
Barclays' equities traders, meanwhile, posted a 47% jump in revenue.