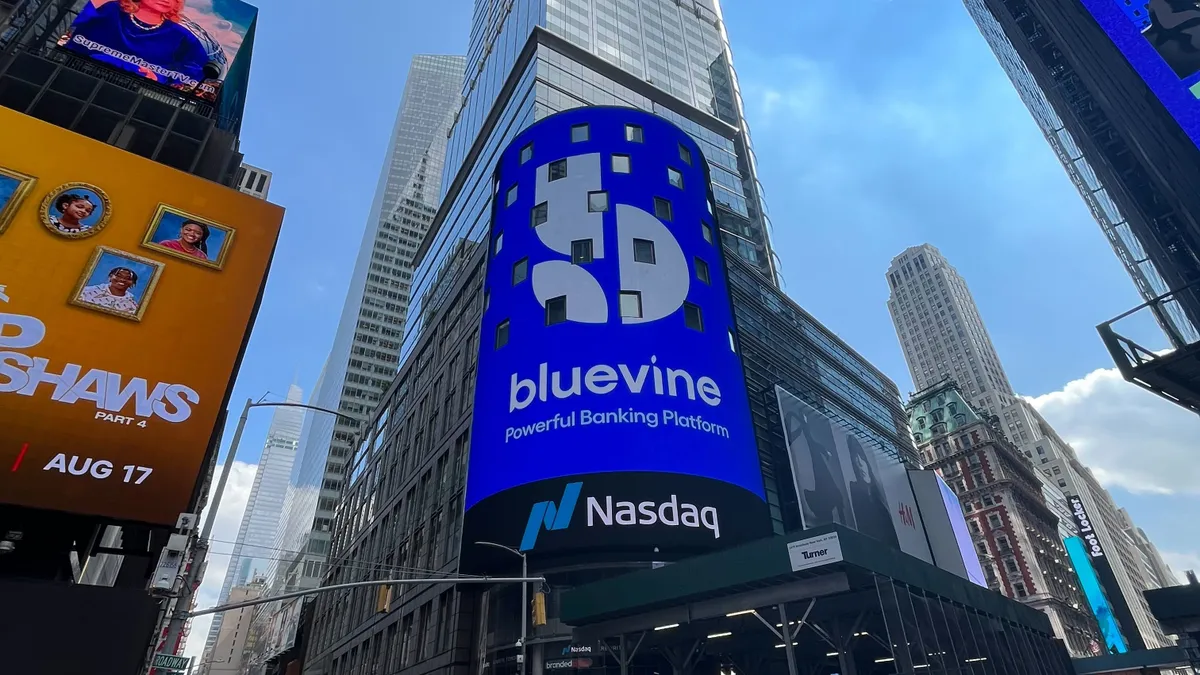
Since agreeing to sell small-business banking fintech Bluevine to Valley National Bank in September, founder and CEO Eyal Lifshitz said his confidence in the firms’ match boils down to three things.
“One, do we get to do what we are excited and passionate about? Two, do we like our day-to-day? And three, do we like the people that we're going to be working with?” he said.
The deal, thus far, has all three passing with flying colors, according to Lifshitz.
“We feel like [the deal] puts us in a really good position to not just continue doing what we're doing, but actually accelerate that,” Lifshitz said in an interview at the Money20/20 conference in Las Vegas. “It’s easy to get myself and the team excited about [what we do], but at scale, with the backing and the benefit of being part of Valley? That brings a lot to the table.”
Morristown, New Jersey-based Valley will pay $340 million in cash and stock for Bluevine, which brings with it $2.1 billion in deposits and 175,000 active small-business clients. The deal is set to close early in 2027, after which Lifshitz will oversee Valley’s small-business arm, including the bank’s legacy small-business clients.
With Lifshitz as head of small-business banking, Valley will be able to “bring [the businesses] together the right way,” said the bank’s chief operating officer, Russ Barrett.
“Running them individually is just going to end up where you have this traditional bank on one side, and you have a very modern digital bank on the other side,” Barrett said. “The right way to do what we're talking about here is to say, it's one segment with one very clear leader who has a vision and a passion for what we could do with that.”
Valley has acquired five banks over the past decade (the fifth of which, Chicago-area’s Providence Bank & Trust, is set to close early next year). But buying a fintech is charting new territory for Valley, Barrett said.
Bank mergers and acquisitions have “a rhythm and a routine that's very well known,” he said, with “pretty robust playbooks.” But buying the fintech has “really unique dimensions that are very different than a bank acquisition.”
“The reality is, we acquired a technology company that was in banking, [which is a] really great experience for us, especially with where banking is going over the next set of cycles,” Barrett said. “But we had to learn and learn fast as we were going through the process to be able to stay relevant for the decisions that Eyal had to make.”
When the deal was announced in September, Valley executives stressed the appeal of bringing Bluevine’s technology and artificial intelligence strategy into the bank. Roughly 180 Bluevine research-and-development employees and engineers will join Valley with the deal, and the fintech’s in-house capabilities will cut the bank’s reliance on third-party providers and improve its speed to market, Valley CEO Ira Robbins said last month.
Bluevine gives the bank a national distribution platform and will grow Valley’s small-business customer base 20-fold, Robbins said.
An M&A meet-cute
The deal grew out of a chance meeting between Lifshitz and Barrett at Money20/20 last year, when neither firm was in search of a deal. But buying that ticket turned out to be “the deal of the century” for Valley, Barrett said: In the spring, Bluevine was exploring becoming a bank through M&A, either as the acquirer or the acquired, and he recalled his meeting with Barrett several months prior.
“If I'm going to go down this path, I might as well choose what would be the best fit for us,” Lifshitz thought. He reached out, and two days later, he was in Barrett’s office.
One year later, Barrett stressed that the “secret sauce” of how both Valley and Bluevine show up with clients is relationship banking – Valley, with community presence; Bluevine, digitally.
Combining Valley’s personalized advice with Bluevine’s digital capabilities could create a relationship banking experience few midsize banks can match, he said.
“When you think about what the next 100 years of banking are going to be like, digital is how you deliver trust,” Barrett said. “It's not just about the person who you see who's connected in your local community and part of your neighborhood activities. It's also going to be, how do they show up repeatedly and consistently, thinking about what your needs are, anticipating how to serve you, and I think that's what digital offers. And Bluevine has been obsessed over doing that.”