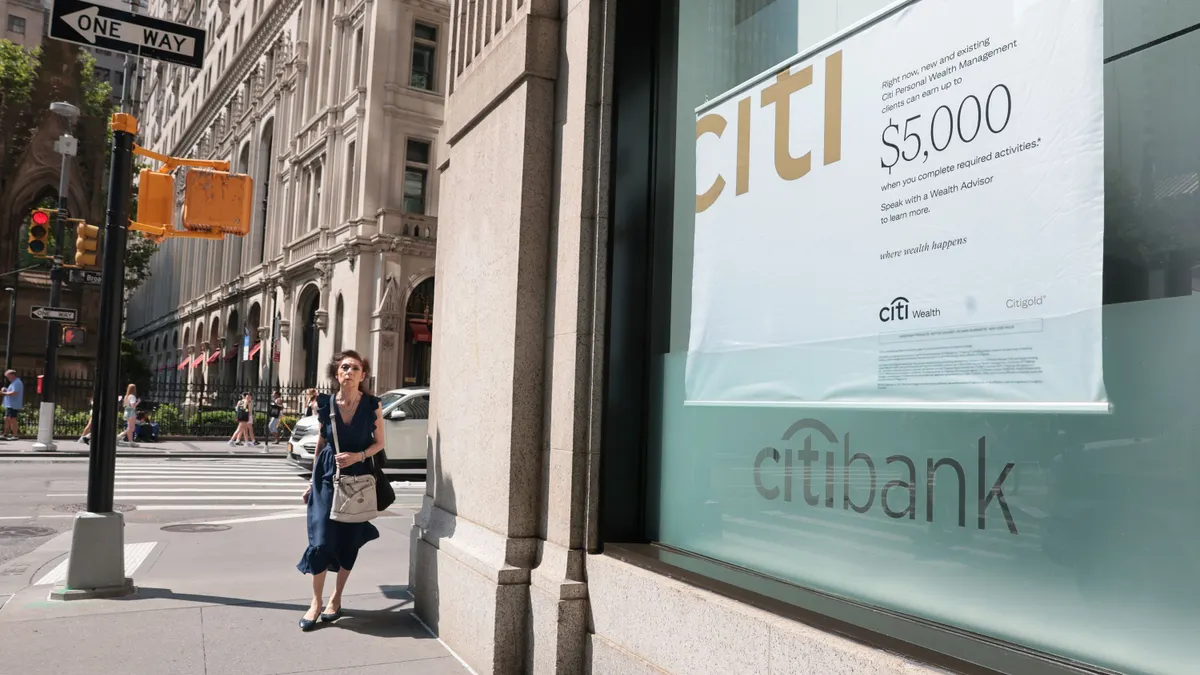
Citi is offering its customers higher savings rates as an incentive to bring more of their money to the bank, as part of the lender’s push to deepen client relationships.
“With the industry being so focused on promotions, you see a lot of money in motion,” said Kate Luft, Citi’s head of retail banking. “This is a disruptor to stop money in motion.”
The $2.6 trillion-asset lender seeks to draw in more of its customers’ $3 trillion in assets not held at the bank, and premium boost, announced last month, is an effort to nudge clients toward consolidation, she said. It builds on Citi’s move to simplify its retail banking products with relationship tiers, similar to airlines, based on a customer’s deposits and investments at the bank.
“We’re trying to reward behavior clients are already doing – investing or banking – but not always with us,” Luft said in an interview.
The bank said Monday it will offer Citigold private clients a 4.35% annual percentage yield, Citigold customers 4% and Citi Priority clients 3.5%, if they also have a checking account and a certain direct deposit amount flowing into the account or maintain an average balance in investment accounts.
The three tiers range from $30,000 to $1 million-plus in combined average monthly balance.
Luft said the “always-on” savings boost is the final component of the bank’s value proposition intended to fuel growth in Citi’s retail bank, which counts about 4 million customers and is part of the lender’s wealth segment. Citi declined to share a specific retail deposits figure.
The New York City-based lender had about $900.9 billion in domestic deposits overall, or about 4.7% of the U.S. deposit market share, according to Federal Deposit Insurance Corp. data as of June 30.
Customers tend to move money around to capture promotions, which they’ve grown tired of, Luft contended.
Clients “have savings over here, they have their direct deposit here, and they might have their 401(k) over there. No one actually wants that,” she said. But banks haven’t given them a reason to consolidate their banking, lending and investing in one place, she said.
As the bank conducted customer research, Luft said one noted, “This feels like a wealth strategy, not a short-term banking promotion.”
Premium boost is intended to be “an accelerant” to attract new retail bank clients as well as retain and grow assets from existing clients, Luft said.
To be sure, Citi is competing with an array of banks and fintechs chasing more business with existing customers, and boosting the rewards and value they offer clients to do so.
Luft said the bank’s third-quarter results indicate retail bank changes are bearing fruit.
In the bank’s wealth unit, Q3 average deposits rose 3%, partially offset by a decline in Citigold and retail banking deposits, according to earnings materials.
But Luft pointed to the cash-to-investments shift. About 85% of the bank’s investment assets come from deposits, “so the shift into investment is a great thing,” she said.
The wealth unit logged $38 billion in net new investment assets in Q3, and Citigold and retail bank revenues rose 16%, to about $2.3 billion, fueled by higher deposit spreads, the bank said.
Of the $3 trillion not at Citi, about $2 trillion is in the mass-market space, Luft said, and Citi recently moved to waive fees for everyday consumer checking account customers 23 and younger, and rolled out a new digital direct deposit enrollment.
Next up: The bank is making a “larger investment in marketing” next year, to draw more attention to the bank’s retail enhancements, Luft said.
“The marketing we're focused on doing is really being relevant for clients and explaining that value proposition and how it builds on the relationship model,” she said.
Citi is also working on a “similar revamp” of its small business banking value proposition, set to launch in the second half of 2027, Luft said.