Dive Brief:
- Kansas City, Missouri-based UMB Financial Corp. has agreed to buy Placerville, California-based El Dorado Savings Bank in a cash-and-stock deal valued at $506 million, the banks said Tuesday.
- With El Dorado, $70.8 billion-asset UMB would gain about $2.4 billion in assets, $2.1 billion in deposits, $500 million in loans, along with 31 branches in California and four in Nevada.
- The deal, UMB’s first since its $2 billion purchase of Denver-based Heartland Financial received regulatory approval in January 2025, is expected to close in the first quarter of 2027.
Dive Insight:
Buying El Dorado would grow UMB’s overall branch network to 227 locations across 15 states. The federal savings bank, founded in 1958, serves the Sacramento and Lake Tahoe areas.
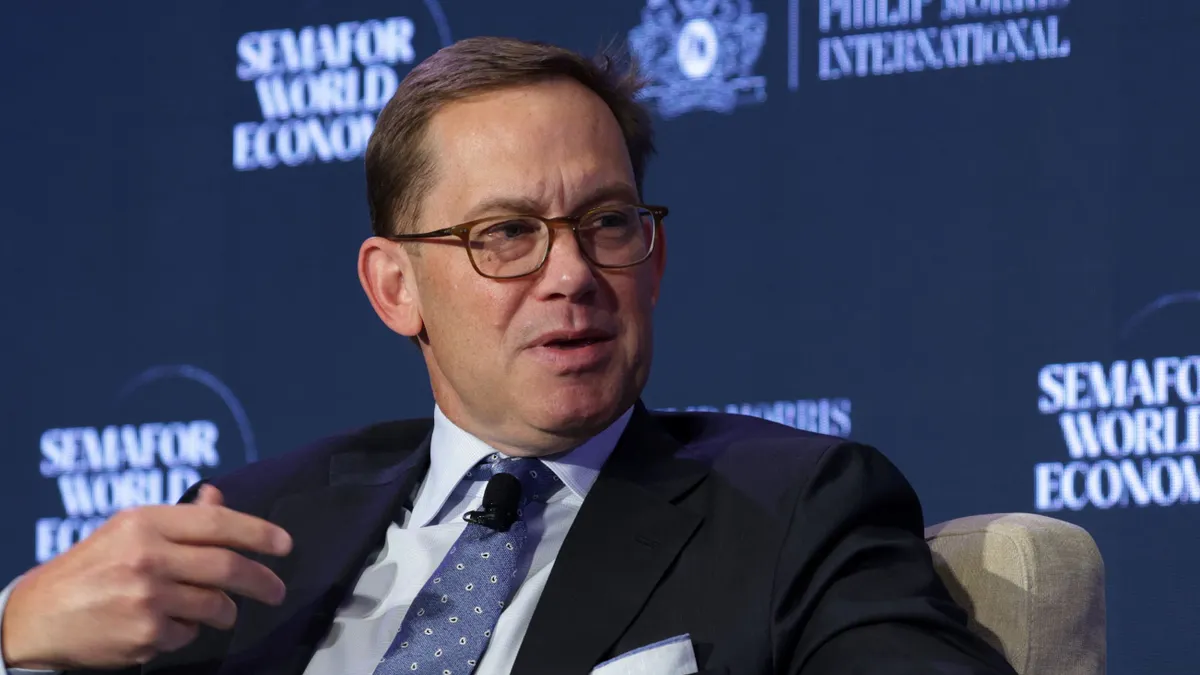
“This milestone is a significant leap forward for our retail footprint and overall presence in California and expands our UMB branch network into Nevada,” UMB CEO Mariner Kemper said in Tuesday’s release. “Since growing our California presence with the HTLF acquisition in 2025, the region’s vibrancy, complementary customer needs and overall business growth opportunities have made it incredibly compelling for our next phase of expansion.”
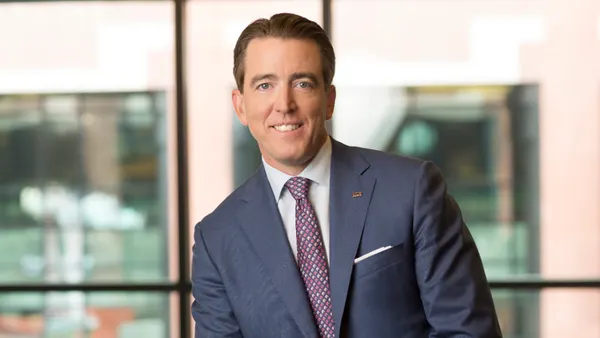
El Dorado CEO David O. Cook will serve as vice chair of UMB Bank California, according to the release.
“This transaction will greatly benefit our customers, communities and shareholders,” Cook said in the release. “We will be able to offer more products and services and do even more to support and uplift our communities. We look forward to continuing the great work we’ve been doing in an even more meaningful and impactful way.”
Under the terms of the 52% cash/48% stock transaction, El Dorado shareholders will receive 13.553 shares of UMB stock, plus an additional $1,958.88 in cash for each outstanding El Dorado share, UMB said.
The $506 million price tag represents an 8% deposit premium, according to an investor presentation. The transaction is expected to be “modestly accretive” to 2027 earnings, UMB CFO Ram Shankar said during the bank’s third-quarter earnings call Wednesday.
UMB’s near-term goal with the smaller lender is to “do no harm,” Kemper said during the call.
El Dorado, which has a total deposits cost of less than 1%, has a significant presence around Lake Tahoe and in Reno, Nevada, according to the presentation. That area offers long-term upside as wealth migrates from California to Nevada in pursuit of a better tax environment, Kemper noted.
El Dorado has already benefited from that, and “we think we can kind of double down on that,” Kemper said.
Truist Securities analyst Brian Foran, in a Wednesday note, said it seems like a “sensible deal,” although “some likely argue that this is a stepping stone, and there could be more acquisitions to come in California over time.”
In February 2025, Kemper indicated more acquisitions would be on the horizon, telling Banking Dive UMB is “one of the consolidators,” as the number of banks in the U.S. shrinks.
About a year later, Kemper took a more measured tone on acquisitions, saying the bank prioritized organic growth but would keep an eye out for tuck-in deals. Investor attitudes toward acquirers have pushed some bank CEOs to express more reluctance around making acquisitions.
With HTLF, UMB executives learned “expectations should be more muted for growth out of the acquired company” between close and conversion, Kemper said in January. “We witnessed that.”
Additional M&A isn’t off the table while UMB absorbs El Dorado, if the right deal comes along, Kemper said. But UMB’s future purchases would be small enough that the lender could maintain control of culture, management and board, Kemper said Wednesday, repeating the “tuck-in” preference.
He didn’t put an asset figure to it, but Kemper said he isn’t interested in a deal size that would involve UMB giving up board seats.
“I like my board, and I don’t need somebody else’s board,” Kemper said.
And as UMB approaches $100 billion in assets, a threshold that carries stricter regulatory requirements, “we would not do a deal that would put us on top of that number,” Kemper said. “While we have a plan, we're not ready today.”
The Kansas City-based bank is interested in acquiring quality, core deposit franchises, which tend to be retail-based purchases, Kemper added.
“We don’t need somebody else’s lending prowess; we’ve got a lending juggernaut,” Kemper said. “We don’t need to pick up somebody else’s problems.”